Nevada Has the Second-Worst Foreclosure Rate in the Country. Only 1 Percent of Las Vegas Sales Are Distressed
Related Stories
Mortgage Rates Hit 7% in Las Vegas
Las Vegas Sellers Pay Concessions 2 of 3 Times
Best Week to Buy a Home in Las Vegas
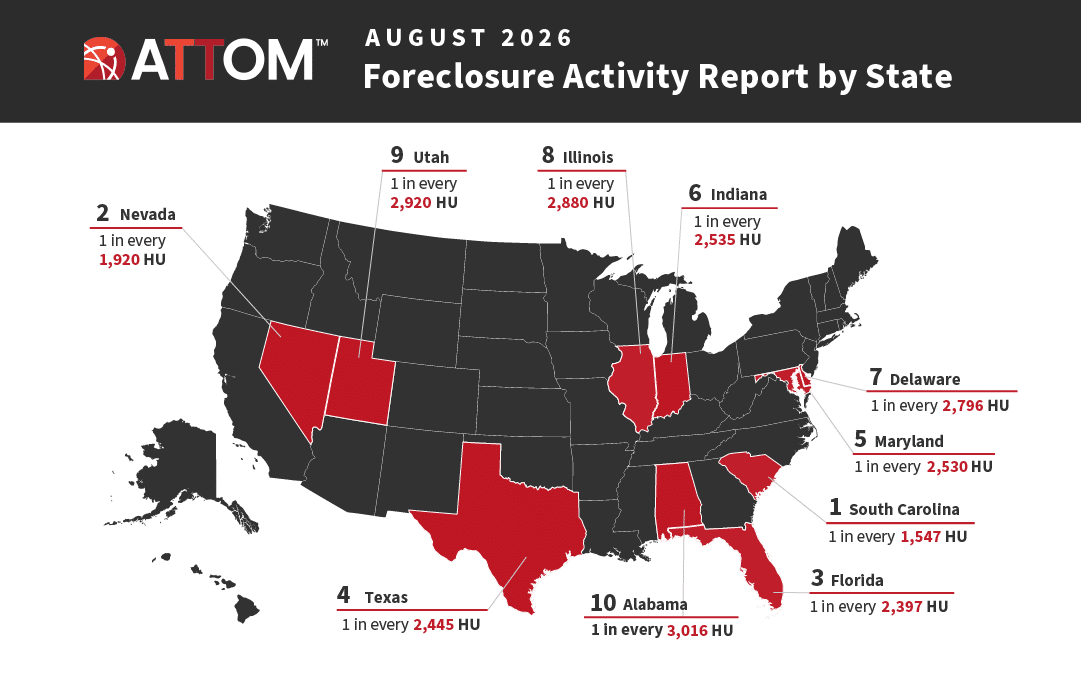
Nevada had the second-worst foreclosure rate in the country in August, with one filing for every 1,920 housing units, according to ATTOM. But in Southern Nevada, only 1.0% of the homes that actually sold in August were short sales or foreclosures, according to Las Vegas REALTORS. That is about 1 sale in every 100.
Those two numbers sound like they come from two different states. They do not. They measure two different things. One counts paperwork filed against homeowners who are behind. The other counts homes that actually changed hands. If you own a home in Las Vegas, Henderson, or North Las Vegas, or you are thinking about buying one, the second number tells you far more about the market you are living in.
We already covered the ranking itself in our earlier post, Nevada Posts the Nation's Second-Worst Foreclosure Rate in August. This article is the follow-up. It is about what the ranking actually means for you: the per-home math, why the share of distressed sales doubled but is still tiny, what to do if your own mortgage is getting hard to pay, and what buyers should expect from bank-owned homes this fall.
What the Numbers Actually Say
ATTOM is a national property data company. On September 17, it released its August 2026 U.S. Foreclosure Market Report. Across the country, 40,277 properties had a foreclosure filing in August. That was up 1% from July and up 13% from August 2025. The national rate worked out to one filing for every 3,569 housing units.
Nevada logged 691 filings across about 1.33 million housing units. That is the one in 1,920 rate, and it put Nevada behind only South Carolina. ATTOM listed Clark County among the Nevada counties with the most foreclosure activity, along with Lyon, Nye, and Mineral counties. It did not publish a separate rate for Clark County or for the Las Vegas metro. And Las Vegas was not one of the five worst metro areas in the country. Those were Columbia, SC; Punta Gorda, FL; Spartanburg, SC; Fayetteville, NC; and Charleston, SC.
ATTOM also broke out the first step of the process. Lenders started foreclosure on 25,894 U.S. properties in August. That was down 3% from July but up 7% from a year earlier. Florida, Texas, and California led the nation in foreclosure starts. So the national picture is mixed. New cases slowed a little from the month before, while the older cases that were already in the pipeline finished at a faster pace.
Now for the local side. Las Vegas REALTORS reported that short sales and foreclosures combined made up 1.0% of all existing local property sales in August, as reported by FOX5 Vegas. A year earlier, that share was 0.5%. So yes, it doubled. But FOX5 also noted that distressed sales remain near historically low levels.
Here is the per-home math in plain terms. One filing per 1,920 homes is about 0.05% of homes in a single month. Picture a large master-planned neighborhood with 2,000 houses. In a month like August, you would expect about one of those homes to have a foreclosure filing of some kind. Now look at sales. Las Vegas REALTORS counted 2,252 existing homes, condos, and townhomes sold in August. One percent of that is about 22 or 23 distressed sales for the whole valley in a month. (That is our own rough math from the reported figures.) Every other sale, roughly 2,230 of them, was a normal sale by a normal owner.
Why It Matters to Las Vegas Homeowners and Buyers
The big thing to understand is that a foreclosure filing is not a lost home. ATTOM counts three kinds of filings: default notices, scheduled auctions, and bank repossessions. A default notice is the very first step. It means a lender has formally said the borrower is behind. Many of those cases never end in a sale. The owner catches up, works out a new payment plan, refinances, or sells the house on their own terms.
That is why the two numbers can be so far apart. The ATTOM rate is an early warning light. The Las Vegas REALTORS number is what actually hit the market. When only about 1 in 100 sales is distressed, it tells you that most owners who hit a rough patch are finding a way out before the bank takes the house.
Let's talk about the word "doubled," because it will show up in headlines. Going from 0.5% to 1.0% is a 100% jump, and that sounds scary. In real terms, it means that out of every 200 local sales, the number of distressed ones went from one to two. That is a real change and it is worth tracking. It is also still a very small slice of the market. A doubling from a tiny number is still a small number. When someone quotes the percent change without the actual share, ask them for the actual share.
For homeowners, the ranking does not change what your home is worth. The August median price for an existing single-family home in Southern Nevada was $475,000, down 1.0% from a year earlier and a bit below the $490,000 record set in May and June. Las Vegas REALTORS President George Kypreos told FOX5 that local prices have been pretty stable for about two years. Stable prices plus a thin slice of distressed sales is not what a foreclosure wave looks like.
For buyers, the takeaway cuts both ways. If you were hoping a "second-worst in the nation" headline meant a flood of cheap bank-owned homes, the local data says that is not coming right now. About two dozen distressed sales a month across the whole valley is not enough to build a home search around. But buyers do have more room than they did a year ago for other reasons. By the end of August, there were 7,590 single-family homes listed without an offer, up 5.3% from a year earlier. The market had just over four and a half months of supply. And 74.8% of homes sold within 60 days, down from 77.5% a year ago. More choices and slower sales give buyers leverage without any foreclosures at all.
The one number worth watching is bank repossessions. Nationally, lenders completed 5,794 foreclosures in August, up 22% from July and up 42% from a year ago. Those completed foreclosures are the homes that become bank-owned listings, often called REOs. ATTOM's top states for REOs in August were Texas, California, North Carolina, Arizona, and Alabama. Nevada was not on that list. Still, a rise in repossessions nationally is the reason we expect a few more bank-owned homes to show up here over time.
Background: Why a High Rate and a Low Share Can Both Be True
Nevada tends to rank high on foreclosure rate lists for a simple reason. The rate is filings divided by all housing units. Nevada has fewer housing units than big states like Florida or Texas, so a few hundred filings move the rate a lot. In August, Florida had 4,278 filings and Texas had 4,961. Nevada had 691. Nevada ranked worse because of the ratio, not because it had more filings.
The share of distressed sales works differently. It is the number of short sales and bank-owned sales divided by all sales that closed. That number stays low when owners have options. In Las Vegas, many owners bought or refinanced years ago and have built up equity. An owner with equity who falls behind can usually sell the home, pay off the loan, and walk away with money instead of a foreclosure on their record. That keeps distressed sales rare even when filings tick up.
It also helps to look at who is buying. In August, 21.9% of local sales were cash deals, down from 22.9% a year earlier. Las Vegas REALTORS noted that the cash buyer share peaked at 59.5% in February 2013, back when the valley was still working through the last housing bust and investors were buying up distressed homes. Today's cash share is less than half of that peak. That is another sign we are not in a distressed-driven market.
National context matters too. ATTOM's CEO, Rob Barber, said in the report that overall foreclosure volumes remain well below historical norms. ATTOM also said overall activity is still below pre-pandemic levels. So the national story is a climb from a very low base, and the local story is a doubling from an even lower base.

What Happens Next
ATTOM releases its foreclosure report every month, and Las Vegas REALTORS releases local sales data each month as well. The September numbers will show whether Nevada holds near the top of the state list, and whether the local distressed share stays around 1% or keeps climbing. A move from 0.5% to 1.0% is worth watching. A move from 1.0% to 3% or 4% would be a real change in the market. We are not there.
Mortgage rates are the other piece to watch. Freddie Mac's 30-year fixed rate crossed 7% this week for the first time since January 2025, as we covered in our mortgage rate breakdown. Higher rates do not push current owners into foreclosure, because most people have a fixed rate. But they make it harder for a struggling owner to refinance their way out of trouble, and they slow down buyers. If homes take longer to sell, an owner who needs to sell fast has less room for error. That is why the time to act is early, not after the second or third missed payment.
On the buyer side, expect a slow trickle of bank-owned listings, not a wave. If national repossessions keep rising, some of those homes will land in Clark County. They will show up in the same listings every buyer sees, and they will compete with regular sales that often come with seller help on closing costs or rate buydowns.
Ryan's Take
Every time a foreclosure ranking comes out, I get the same two texts. Homeowners ask if their value is about to crash. Buyers ask if they should wait for the foreclosures. My honest answer to both is no. The ranking is real, and I take it seriously. But about 1 in 100 local sales being distressed tells me that owners who hit a wall are mostly selling on their own terms, with their equity intact. That is the opposite of what we saw after the last bust.
What I tell buyers is this: do not build your plan around bank-owned homes. There are not enough of them. Build your plan around the leverage that already exists. Inventory is up, homes are taking longer to sell, and sellers are saying yes to concessions. If a good REO pops up in your price range, we will look at it. But waiting for a wave that the local data does not show could cost you a good home and a year of equity. And if you are a homeowner who is starting to fall behind, please call someone early. The owners who get through a hard stretch are almost always the ones who acted first.

What You Can Do
If you are a homeowner under strain, call your mortgage servicer as soon as you know a payment will be late. Ask what options they have, such as a repayment plan, a forbearance, or a loan modification. Write down who you talked to and when. Next, talk to a HUD-approved housing counselor. The Consumer Financial Protection Bureau has a free search tool that lists approved counselors by ZIP code, and many offer help at little or no cost. Nevada also has a foreclosure mediation program through the state court system that eligible owners can use once a default notice is recorded. A counselor can walk you through it. Be careful with anyone who asks for money up front to "save" your home.
If you have equity, selling may be your best option, and it is far better than a foreclosure. With the median at $475,000 and many owners holding years of equity, a planned sale can pay off the loan and protect your credit. A quick call can tell you what your home would likely sell for and how long it might take in today's market.
If you are a buyer, know that bank-owned homes are usually sold as-is. Plan on a full inspection, slower responses from the bank, and extra paperwork. Get pre-approved, keep an eye out for REOs in your price range, but do not pass on a good regular listing while you wait. Right now, sellers of regular homes are often offering help with closing costs, which can be worth more than any foreclosure discount.
If you are a neighbor or a renter, the practical effect on your street is small. At about 22 distressed sales a month across the whole valley, you are not likely to see a row of empty homes on your block. If you rent a home and get a notice that your landlord is in foreclosure, do not ignore it. Read it carefully, keep paying rent as your lease requires, and reach out to a housing counselor or legal aid office to learn your rights before you make any moves.
If you just want to keep an eye on things, watch two numbers each month. The first is ATTOM's state ranking, which tells you about filings. The second is the Las Vegas REALTORS distressed share, which tells you about actual sales. As long as the second number stays low, the first number is a warning light, not a crisis.

Have questions about how this affects your home or neighborhood? Reach out to Ryan Rose or text/call 702-747-5921 anytime.
Sources
ATTOM: FORECLOSURE ACTIVITY REMAINS ABOVE YEAR-AGO LEVELS IN AUGUST 2026
ATTOM: U.S. Foreclosure Rates by State, August 2026
FOX5 Vegas: Report: Las Vegas home prices dip again in August, sales slow
Consumer Financial Protection Bureau: Find a Housing Counselor
Categories
- All Blogs (4796)
- Absentee Owner (4)
- Affordability (3)
- ALIANTE (53)
- Anthem (33)
- Ascension (50)
- Assumable Loan (1)
- Astra (50)
- BLACK MOUNTAIN (55)
- Buyers (22)
- Cadence (17)
- Calico Ridge (50)
- Canyon Fairways (50)
- CANYONS OF SUMMERLIN (55)
- CENTENNIAL HILLS (81)
- Comparisons (46)
- CROSSINGS IN SUMMERLIN (55)
- DESERT SHORES (47)
- Divorce (3)
- Downsizing (13)
- EAGLE HILLS (55)
- Empty Nester (1)
- Enterprise (1)
- EXPIRED LISTINGS (134)
- First Time Homebuyer (4)
- Green Valley (139)
- Henderson (82)
- HORIZONS EDGE (50)
- Housing Market Trends (100)
- Informative (112)
- Inspirada (58)
- Lake Las Vegas (2)
- Lakes Las Vegas (3)
- Las Vegas Real Estate (182)
- Local News (591)
- Luxury (1)
- MacDonald Highlands (88)
- MacDonald Ranch (100)
- Madeira Canyon (93)
- MESQUITE NV (103)
- MOUNTAIN TRAILS (50)
- Mountains Edge (79)
- Naked City (35)
- New Construction (131)
- North Las Vegas (24)
- Northgate (23)
- PALISADES SUMMERLIN (50)
- Probate (28)
- Providence (2)
- Quail Ridge (35)
- QUEENSRIDGE (56)
- Red Rock (1)
- RED ROCK COUNTRY CLUB (60)
- Relocating to Summerlin (207)
- Relocation (45)
- Retired (1)
- Retirement (1)
- Reverence (15)
- RHODES RANCH (64)
- Ridgebrook (40)
- Sellers (255)
- Seven Hills (83)
- Silverado Ranch (1)
- Silverstone Ranch (39)
- SKYE CANYON (100)
- SKYE CANYONE (4)
- Southern Highlands (94)
- Southwest (19)
- SPANISH TRAILS (55)
- SPRING VALLEY (70)
- Summerlin (104)
- Sun City Summerlin (3)
- The Arbors (37)
- The Cliffs (50)
- THE HILLS (55)
- THE PASEOS (55)
- The Pueblos (27)
- THE PUEBLOS OF SUMMERLIN (42)
- THE RIDGES (65)
- THE VISTAS OF SUMMERLIN (50)
- The Willows (60)
- Thoughts on Home Tour (2)
- TOURNAMENT HILLS (50)
- Veterans (3)
- WHITNEY RANCH (55)
- Workers Advantage Program (100)
Recent Posts




GET MORE INFORMATION